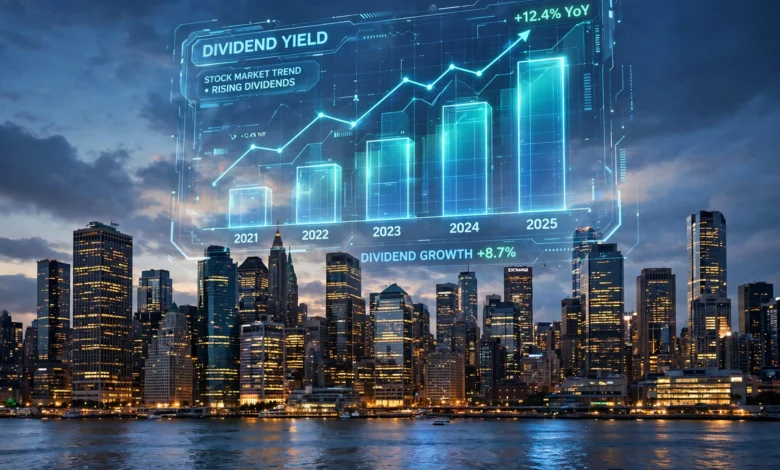
If you are evaluating BLK stock through an income investor’s lens rather than a growth trader’s, the headline numbers are straightforward: BlackRock pays an annual dividend of $22.92 per share, worth a yield of roughly 2.0–2.05% at recent prices, and it has now raised that payout for 16 consecutive years — a record that puts it in rare company among large financial stocks. This article is not a buy-or-sell call and is not financial advice; it is a factual walkthrough of BLK’s dividend history, how safe the payout looks, and how it stacks up against rival asset managers for yield, all based on data current as of October 2026.
BLK Stock for Income Investors
For investors who care more about dependable cash flow than share-price fireworks, BlackRock presents an interesting income profile: a modest absolute yield of about 2.0% backed by one of the most consistent raise streaks in the asset-management industry, with the payout comfortably covered by recurring fee income from managing trillions in client assets. The quarterly dividend currently stands at $5.73 per share — paid on 22 September 2026 with an ex-dividend date of 8 September 2026 — and with three quarterly payments made so far this year, the 2026 year-to-date total sits at $17.19, with the next payment estimated around 23 December 2026, according to StockAnalysis.com’s BLK dividend data.
That 2.0% yield will never excite a pure income hunter, and BlackRock would be the first to tell you it is a dividend-growth story rather than a high-yield play — the kind of stock bought for a payout that climbs reliably year after year rather than one that pays lavishly today. One-year dividend growth runs at 8.06%, and the payout ratio sits near 52%, meaning roughly half of earnings are returned to shareholders while the rest funds the business, a balance that dividend analysts generally read as sustainable rather than stretched.
The Raise-by-Raise History (2021–2026)
The dividend record is where BlackRock quietly earns its reputation: sixteen consecutive years of increases, with the annual payout climbing from $16.52 in 2021 to $19.52 in 2022, $20.00 in 2023, $20.40 in 2024 and $20.84 in 2025, per the dividend tables tracked at StockEvents. The March 2026 raise lifted the quarterly payout 9.98% — from $5.21 to $5.73 — one of the more generous bumps in recent years and a signal that management remained confident in fee income even amid market volatility.
Zoom out further and the compounding tells the story income investors actually buy: five-year dividend growth averages 6.93% annually, and three-year growth averages 4.06%, which means the payout has been growing well ahead of inflation through very different market regimes. That consistency is the product of BlackRock’s business model — recurring management fees on client assets produce steadier cash flows than trading or lending income — and it is precisely why dividend-growth funds, rather than high-yield chasers, are the natural audience for this stock.
How Safe Is the Dividend?
Dividend safety comes down to coverage, and on that measure the payout looks well-defended: a payout ratio of roughly 52% leaves nearly half of earnings retained, giving the dividend a comfortable cushion against a single bad quarter, and the payout is funded by recurring fee income — the management fees BlackRock collects on its vast asset base — rather than by volatile trading profits or one-off gains. That fee-income foundation is the structural reason the dividend has survived market sell-offs, rate cycles and the occasional asset-management industry fee war without a cut.
The honest caveat is concentration: because the payout depends on fee income tied to the value of assets under management, a severe, prolonged market drawdown would squeeze both the share price and the earnings coverage simultaneously, narrowing that comfortable cushion. No dividend is guaranteed, and BlackRock’s board reviews the payout quarterly — but sixteen years of uninterrupted increases through bull markets, bear markets and a pandemic-era crash is about as strong a track record of board-level commitment as a large-cap financial stock can offer.
BLK vs State Street vs T. Rowe Price: The Yield Showdown
Put BlackRock beside its two most comparable listed rivals and the income trade-offs snap into focus. At the 23 October 2026 close, BlackRock traded at $1,118.25 with a P/E of 26.5 and a market capitalization of $183.4B, yielding roughly 2.0–2.1%; State Street traded at $167.83 with a P/E of 12.4 and a $45.7B market cap, yielding around 2.6–2.9%; and T. Rowe Price traded at $104.20 with a P/E of 9.8 and a $21.8B market cap, yielding approximately 5.0%, based on live market data via Finnhub and yield data compiled by the Fool in October 2026.
The pattern is unmistakable: the market prices BlackRock for growth and quality — the highest multiple, the lowest yield — while T. Rowe Price is priced as the value-and-income option, with a 5% yield that dwarfs its peers. State Street sits in the middle on both valuation and yield. T. Rowe Price pays roughly $5.17 annually with a payout ratio near 54%, remarkably similar in sustainability to BlackRock’s 52%, though T. Rowe places a heavier emphasis on share buybacks alongside its dividend. In short, BLK is the dividend-growth play in this trio and TROW is the high-yield play — and neither framing is “better” in the abstract, because they serve entirely different income objectives.
Dividend Growth vs High Yield: The Trade-Off
Choosing between BLK stock and a higher-yielding rival is really a choice between two different income philosophies, and understanding the trade-off matters more than the headline yield number. A 2% yield growing at 7% a year doubles its payout roughly every decade, so an investor buying BlackRock today is effectively buying a much larger future income stream — while a 5% yield growing slowly pays generously now but may barely keep pace with inflation over time. The crossover point, where the faster-growing smaller yield overtakes the slower-growing larger one, typically arrives within a decade for growth rates like BlackRock’s, which is why dividend-growth investors are willing to “pay up” in valuation terms.
There is also a quality signal embedded in the growth: a company that raises its dividend sixteen years running is demonstrating, year after year, that its cash flows are real, recurring and expanding — a discipline that high headline yields do not always prove. None of this makes BlackRock right for an investor who needs maximum income this year, such as a retiree drawing down a portfolio; for that objective, T. Rowe Price’s 5% yield is the more honest fit. The right question is never “which yield is bigger” but “which income shape matches my timeline” — and that answer is personal, not universal.
Risks for Income Investors
The specific risk that should sit at the top of any income investor’s checklist is the fee-income dependency described earlier: BlackRock’s dividend is paid from management fees on client assets, so a deep market drawdown reduces assets under management, compresses fee revenue and narrows dividend coverage all at once — the share price falls and the payout’s safety margin shrinks in the same move. That double exposure is the price of the business model’s otherwise admirable consistency, and it is why even a sixteen-year raise streak deserves monitoring rather than blind trust.
Beyond market risk, the asset-management industry faces slow-burn pressures that matter for a multi-decade income thesis: ongoing fee compression as passive investing grows, regulatory scrutiny of the industry’s largest players, and periodic political controversy around environmental and governance investing stances. None of these has threatened the dividend yet, but each is a variable that could, over time, pressure the fee margins that fund it. The prudent approach for a BlackRock income holder is the same as for any single-stock dividend position: treat it as one leg of a diversified income portfolio, reinvest or collect deliberately, and review the payout ratio and raise announcements each year rather than assuming the streak runs itself.
Conclusion
Viewed purely as an income investment, BLK stock offers a clear and honest proposition: a roughly 2% yield today, a $22.92 annual payout, sixteen consecutive years of raises, a sustainable ~52% payout ratio, and a business model built on recurring fee income rather than cyclical windfalls. It will never win a yield contest against T. Rowe Price’s 5%, but it was never trying to — BlackRock is the dividend-growth compounder of the asset-management world, and its long-term holders have been paid increasingly well for their patience.
For 2026, the income outlook rests on the same foundation as always: as long as client assets and fee income hold up, the board has every incentive to extend the streak to seventeen years, with the December quarterly payment the next checkpoint to watch. Keep an eye on the payout ratio and each year’s raise announcement, diversify across income styles rather than betting on one, and remember this is information, not financial advice. And if you enjoy digging into what serious money actually buys beyond the portfolio, our breakdown of the Tesla Model Y lineup and UK pricing is another corner of the site where we unpack value for money in detail.
How Much Dividend Does BLK Stock Pay?
BLK stock pays an annual dividend of $22.92 per share, distributed in quarterly payments of $5.73 — the most recent quarterly payment was made on 22 September 2026 with an ex-dividend date of 8 September 2026. That annual payout translates to a dividend yield of roughly 2.0–2.05% at recent share prices, according to dividend data from StockAnalysis.com and StockEvents, current as of October 2026. Three quarterly payments have been made so far in 2026 for a year-to-date total of $17.19, with the fourth quarterly payment estimated around 23 December 2026. The payout ratio sits near 52%, meaning about half of earnings are returned to shareholders.
How Long Has BlackRock Been Raising Its Dividend?
BlackRock has raised its dividend for 16 consecutive years, one of the longest uninterrupted raise streaks among large US financial stocks. The annual payout has climbed from $16.52 in 2021 to $19.52 in 2022, $20.00 in 2023, $20.40 in 2024 and $20.84 in 2025, with the 2026 trajectory on pace for another record year. The March 2026 increase lifted the quarterly dividend 9.98%, from $5.21 to $5.73. Five-year dividend growth averages 6.93% annually and three-year growth averages 4.06%, well ahead of inflation — the compounding profile that defines BlackRock as a dividend-growth investment rather than a high-yield one.
Is BLK Stock’s Dividend Safe?
By the standard measures, yes — reasonably safe, though no dividend is ever guaranteed. The payout ratio of roughly 52% leaves nearly half of earnings retained as a cushion, and the dividend is funded by recurring management-fee income on client assets rather than volatile trading profits, which is why it has survived market sell-offs and rate cycles without a cut. The main risk is that a severe, prolonged market drawdown would shrink assets under management and fee revenue simultaneously, narrowing coverage just as the share price falls. Income investors should monitor the payout ratio and each year’s raise announcement rather than assuming the sixteen-year streak runs on autopilot.
Which Is Better for Income: BLK, State Street or T. Rowe Price?
It depends on the income objective: BlackRock, yielding about 2.0–2.1% with 16 years of raises, is the dividend-growth play; T. Rowe Price, yielding roughly 5.0% with a similar ~54% payout ratio, is the high-yield play; State Street sits between them at roughly 2.6–2.9% yield. At the 23 October 2026 close, BlackRock traded at $1,118.25 (P/E 26.5, $183.4B market cap), State Street at $167.83 (P/E 12.4, $45.7B) and T. Rowe Price at $104.20 (P/E 9.8, $21.8B). An investor needing maximum income today fits T. Rowe Price better, while an investor prioritizing a payout that doubles roughly every decade at historical growth rates fits BlackRock — different income shapes for different timelines.
When Is the Next BLK Dividend Payment?
Based on BlackRock’s established quarterly schedule, the next BlackRock dividend payment is estimated around 23 December 2026, following the 22 September 2026 payment of $5.73 per share. BlackRock typically announces each quarterly dividend a few weeks before the payment date, with the ex-dividend date falling about two weeks prior — the September payment’s ex-date was 8 September 2026. Shareholders must own the stock before the ex-dividend date to receive that quarter’s payment. Investors should confirm the exact declaration, ex-date and payment date in BlackRock’s official investor-relations announcements, as schedules can shift.
Does BLK Stock Pay a Special or Variable Dividend?
No — BlackRock pays a regular, predictable quarterly cash dividend with no special or variable component in its current policy. The $5.73 quarterly payout is set by the board each quarter and has followed a steady upward path, with the March 2026 increase of 9.98% being the latest raise. Unlike some energy or mining stocks that layer special dividends on top of a base payout depending on commodity prices, BlackRock’s income story is entirely about the dependable, growing base dividend. T. Rowe Price, by contrast, pairs its dividend with a heavier emphasis on share buybacks, another way of returning cash that does not show up in the yield figure.